Current ratio: what it is, formula, and how to calculate it
Learn how to calculate and interpret the current ratio to assess your business's short-term financial health.
Written by Jotika Teli—Certified Public Accountant with 24 years of experience. Read Jotika's full bio
Published Monday 18 May 2026
Table of contents
Key takeaways
- Calculate your current ratio by dividing current assets by current liabilities. A ratio above 1.0 means you have enough assets to cover short-term debts, while a ratio below 1.0 signals potential cash flow challenges.
- Monitor your current ratio monthly to spot trends early and compare it against industry benchmarks, since acceptable ratios vary significantly between sectors.
- The current ratio only provides a snapshot in time and treats all current assets as equally liquid. Pair it with cash flow forecasts and other liquidity metrics like the quick ratio for a complete financial picture.
- Improve your current ratio by speeding up invoice collections, converting excess inventory to cash, negotiating extended supplier payment terms, and paying down short-term debt.
What is the current ratio?
The current ratio is a financial metric that measures your business's ability to pay short-term debts by comparing current assets to current liabilities. As a key liquidity ratio, it shows whether you can cover upcoming bills, loan repayments, and other obligations due within the next 12 months.
You might also see it called the working capital ratio. A ratio above 1.0 means your current assets exceed your current liabilities, while a ratio below 1.0 suggests you may struggle to meet short-term obligations without additional funding.
Why the current ratio matters for businesses
Understanding your current ratio helps you make smarter financial decisions across three critical areas.
Managing short-term obligations
A strong current ratio reflects your ability to pay suppliers, rent, and employee salaries without borrowing additional money. If your current assets are lower than your liabilities, it can be harder to cover bills as they fall due.
You may need to find extra funding to stay on top of payments, so it pays to watch this ratio closely. Tracking it regularly gives you time to act before cash flow gaps become a problem.
Building investor and lender confidence
Lenders and investors look at your current ratio to gauge your business's financial stability. A healthy ratio signals that you can service a loan or generate a return on investment.
Businesses with a strong current ratio typically manage their liquidity well, making them a lower risk for investors. If you're applying for a loan or seeking funding, a solid ratio strengthens your position.
Planning for growth
A healthy ratio shows you have room to invest in growth opportunities. With strong liquidity, you can confidently open a new location, hire staff, or invest in new technology.
A solid current ratio also provides a safety margin against unexpected downturns, helping your business stay agile and take advantage of opportunities as they arise.
Current ratio formula
The current ratio formula divides your total current assets by your total current liabilities.
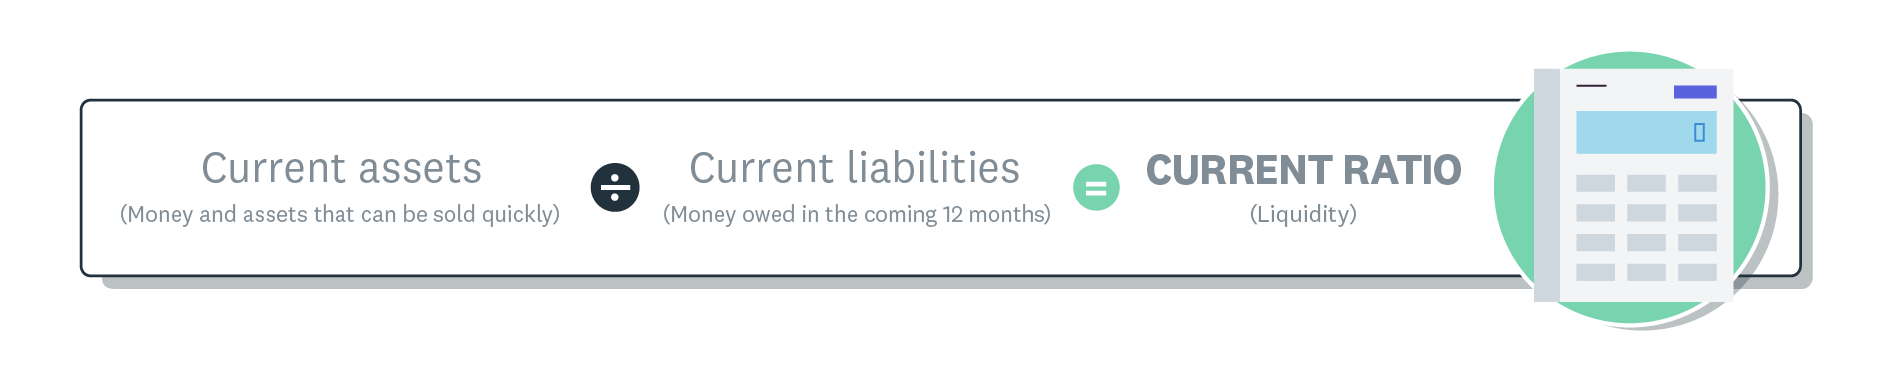
Current ratio liquidity formula.
Current ratio = current assets ÷ current liabilities
You'll find both figures on your balance sheet. Here's more about balance sheets from the U.S. Small Business Administration (SBA).
Components of the current ratio
Current assets are resources you can convert to cash within one year. They include:
- Cash and cash equivalents: money in checking accounts and short-term investments
- Accounts receivable: money customers owe you
- Inventory: products ready for sale or raw materials
- Prepaid expenses: insurance, rent, or supplies paid in advance
Current liabilities are debts you must pay within the same period. They include:
- Accounts payable: money you owe suppliers
- Short-term loans: debt due within 12 months
- Accrued expenses: wages, taxes, or utilities you owe
- Current portion of long-term debt: next year's payments on long-term loans
How to calculate the current ratio
Calculating your current ratio takes just four steps using information from your balance sheet.
- Gather your balance sheet. Pull your most recent balance sheet, which lists all current assets and current liabilities. If you use accounting software, you can generate one in seconds.
- Add up your current assets. Total your cash, accounts receivable, inventory, and prepaid expenses. Only include assets you can convert to cash within 12 months.
- Add up your current liabilities. Total your accounts payable, short-term loans, accrued expenses, and any current portion of long-term debt. Only include obligations due within 12 months.
- Divide assets by liabilities. Divide total current assets by total current liabilities. The result is your current ratio.
Current ratio calculation example
Seeing the formula in action makes it easier to understand what your result means. Here are two examples.
A small construction business wants to determine its current ratio to see if it can cover upcoming loan repayments and material costs. The business has $250,000 in current assets and $175,000 in current liabilities:
$250,000 / $175,000 = 1.43
The ratio is above 1.0, meaning the business can cover its upcoming debts. For every $1 of liabilities, it has $1.43 available. This gives the business room to invest in other areas or keep cash in reserve for unexpected costs.
Now consider a small retail shop with $80,000 in current assets and $100,000 in current liabilities:
$80,000 / $100,000 = 0.80
A ratio below 1.0 means the business doesn't have enough current assets to cover its short-term debts. For every $1 of liabilities, it only has $0.80 available. This signals the business may need to speed up collections, reduce expenses, or secure additional funding.
How to interpret current ratio results
Your current ratio tells you how well your business can meet short-term financial obligations, but the number alone doesn't tell the full story.
A ratio above 1.0 means you have more current assets than current liabilities, so you can cover upcoming debts. The higher the ratio, the larger your cushion. However, a very high ratio (above 3.0) could mean you're holding too much cash or inventory that could be put to better use.
A ratio below 1.0 means your current liabilities exceed your current assets. This doesn't always signal trouble, particularly if you have strong, predictable cash flow coming in. But it does mean you should monitor your finances closely and consider ways to strengthen your position.
Industry context matters. Retail businesses often operate with lower ratios because they turn over inventory quickly, while manufacturing businesses may carry higher ratios due to larger inventory holdings. Compare your ratio against businesses in your sector for a meaningful benchmark.
Track your ratio monthly to spot trends. A declining ratio over several months may signal growing cash flow concerns, even if the number is still above 1.0. Combine it with cash flow forecasts and profitability ratios for a more complete view of your financial health.
What is a good current ratio?
A good current ratio generally falls between 1.5 and 2.0, meaning you have $1.50 to $2.00 in current assets for every $1 of current liabilities. This range suggests your business can comfortably cover its short-term obligations while still putting assets to productive use.
That said, the ideal ratio varies by industry. Service businesses with minimal inventory may operate well at a ratio closer to 1.2, while manufacturing or construction businesses often need a ratio of 2.0 or higher due to longer cash conversion cycles.
A ratio that's too high isn't always a positive sign. If your ratio consistently sits above 3.0, it could mean you're holding excess cash, carrying too much inventory, or not investing enough in growth. Efficient asset use matters just as much as having enough liquidity.
The current ratio is one of several liquidity ratios, which are metrics that measure your ability to meet short-term financial obligations. Other liquidity ratios include the quick ratio and the cash ratio. Using them together gives you a fuller picture of your short-term financial position. Learn more in the liquidity ratios guide.
How to improve your current ratio
If your current ratio is lower than you'd like, there are practical steps you can take to strengthen it. Focus on increasing current assets, reducing current liabilities, or both.
To increase your current assets:
- Speed up collections: follow up on overdue invoices promptly and consider offering early payment discounts to customers
- Liquidate excess inventory: convert slow-moving stock to cash through promotions or clearance pricing
- Optimize cash management: keep appropriate cash reserves and move idle funds into short-term, liquid investments
To reduce your current liabilities:
- Negotiate payment terms: ask suppliers for extended payment periods, such as moving from 30-day to 60-day terms
- Pay down short-term debt: use available cash to reduce immediate obligations when possible
- Restructure financing: convert short-term loans to long-term financing to move debt off your current liabilities
Current ratio vs quick ratio and cash ratio
Each liquidity ratio measures your ability to pay short-term debts, but they differ in which assets they include. Understanding all three helps you get a complete picture of your short-term financial position.
The current ratio uses the broadest definition of assets:
Current ratio = current assets ÷ current liabilities
The quick ratio (also called the acid test) excludes inventory and prepaid expenses, focusing only on assets you can convert to cash within 90 days:
Quick ratio = (cash + accounts receivable + short-term investments) / current liabilities
The cash ratio is the most conservative measure, counting only cash and cash equivalents:
Cash ratio = cash and cash equivalents / current liabilities
Use the current ratio for a broad view of liquidity. Use the quick ratio when you want to exclude slow-moving inventory from the picture. Use the cash ratio to test whether you could cover debts immediately without relying on collections or asset sales. Together, these three ratios give you a layered understanding of your financial flexibility. Learn more in the liquidity ratios guide.
Common pitfalls when using the current ratio
The current ratio is a useful starting point, but it has limitations you should keep in mind.
It only gives a snapshot in time
Like most liquidity ratios, the current ratio shows a single moment in your finances. It doesn't reflect daily changes in cash flow or future income. A ratio calculated today could look different next week if a large payment comes in or goes out.
It treats all current assets as equally liquid
The current ratio doesn't distinguish between types of assets. Cash is immediately available, but inventory or accounts receivable may take weeks or months to convert to cash. Two businesses with the same ratio can have very different abilities to pay bills on short notice.
It ignores the timing of payments
The ratio assumes liabilities are spread evenly over time. In reality, many businesses have uneven or seasonal payment patterns. If your income and expenses vary by season or billing cycle, the ratio might not reflect your true liquidity at any given point.
Inventory valuation can skew results
If your inventory is overvalued on the balance sheet, your current ratio will appear stronger than it actually is. Slow-moving or obsolete stock may not convert to cash at its listed value, inflating your ratio and masking potential liquidity issues.
Seasonal variations affect accuracy
Businesses with seasonal revenue cycles may see their current ratio swing significantly throughout the year. A retailer's ratio could look strong after the holiday season but weak in the off-season. Measuring at consistent intervals and comparing year-over-year helps you avoid misleading conclusions.
Quality of receivables matters
Not all accounts receivable are equally collectible. If a significant portion of your receivables are overdue or from customers with poor payment histories, your current ratio overstates your ability to pay short-term debts. Review the age and quality of your receivables alongside the ratio for a more accurate picture.
Simplify your current ratio tracking with Xero
Xero's accounting software handles the calculations for you, giving you a clear view of the cash available in your business. You can check your latest cash flow at a glance, track spending, and monitor financial performance indicators over time.
Use Xero's reporting features to create forecasts and projections that help you make informed financial decisions. With real-time data at your fingertips, you can spot changes in your current ratio early and take action before small issues become bigger problems. Get one month free.
FAQs on current ratio
Here are answers to frequently asked questions about current ratio.
How does the current ratio help judge a business's ability to pay short-term debts?
A current ratio above 1.0 confirms you can cover short-term obligations; below 1.0, it's worth reviewing your cash position and payment timelines. Checking this ratio before making large purchases or taking on new debt helps you avoid overextending your finances.
Why does the current ratio change over time?
Your current ratio shifts as invoices come in, bills go out, and inventory levels change. Tracking it monthly helps you distinguish normal fluctuations from patterns that need attention.
How does the current ratio vary across different industries?
Industry benchmarks differ widely; manufacturing businesses often have ratios above 2.0, while service businesses may operate comfortably closer to 1.2. Check ratios for similar businesses in your sector to set a meaningful target.
How does the current ratio affect investor decisions and credit evaluations?
Lenders and credit agencies use the current ratio to gauge short-term solvency before approving loans or setting interest rates. A strong ratio can unlock better credit terms, while a weak one may trigger higher rates or additional collateral requirements.
What are liquidity ratios and how do they relate to the current ratio?
Liquidity ratios measure how easily your business can pay short-term debts; the current ratio, quick ratio, and cash ratio are the three most common. Using all three together reveals whether your liquidity depends on cash, receivables, or inventory.
Disclaimer
Xero does not provide accounting, tax, business or legal advice. This guide has been provided for information purposes only. You should consult your own professional advisors for advice directly relating to your business or before taking action in relation to any of the content provided.
Start using Xero for free
Access Xero features for 30 days, then decide which plan best suits your business.